Why Did The Bank Hold Rates ?
The Bank of England has kept Bank Rate unchanged at 3.75%, with the MPC voting 6–3 to hold, although three members preferred an immediate increase to 4.00%.
Inflation rose to 3.1% in August, with higher oil and energy prices adding further pressure. However, the majority of the MPC chose to wait for clearer evidence that these increases are feeding into wider wages and prices.
For mortgage borrowers, the hold doesn’t necessarily mean cheaper fixed rates. Swap rates have risen significantly, reflecting expectations that interest rates may remain higher for longer.
Rates are on hold for now, but the outlook remains uncertain.
Why Are Swap Rates Rising - What Does This Mean For Mortgages ?
The movement in swap rates since 31st July shows how quickly expectations in financial markets can change. Mortgage lenders use these markets when determining the cost of funding their fixed-rate products. When swap rates rise, the cost of offering new fixed-rate mortgages generally increases too.
The 2-year swap has increased by 0.372% and the 5-year by 0.325% since the end of July. If these levels persist, lenders are likely to face continued pressure on their pricing, potentially resulting in higher fixed mortgage rates and the withdrawal or repricing of existing products. This also explains why mortgage rates can move in the opposite direction to Bank Rate.
What matters to fixed-rate pricing is not simply where Bank Rate is today, but where financial markets expect interest rates to be in the years ahead.
18 September 2026 Swaps
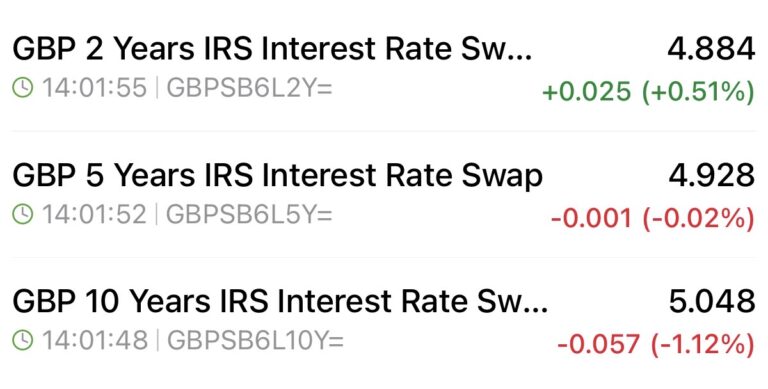
31 July 2026 Swaps

Where Could Interest Rates Go Next ?
Although financial markets are currently pricing interest rates rising towards around 4.9% by the end of 2027, this does not necessarily mean Bank Rate is expected to reach that level. Market pricing includes a significant allowance for risk and uncertainty, particularly around inflation. The Bank of England’s latest survey of market participants paints a less severe picture, with the central expectation for Bank Rate to remain around 3.75% through much of 2027, before falling to 3.50% by the end of 2027 and around 3.25% during 2028.
The important point for mortgage borrowers is that markets are currently demanding a substantial premium against the risk of rates remaining higher or increasing further. This is helping to keep swap rates, and consequently fixed mortgage pricing, higher than might otherwise be expected.
You can also use our online mortgage sourcing tool to check the latest deals available. The system provides real-time mortgage results, allowing you to compare products based on your own circumstances before deciding whether to take advice or secure a rate. This can be particularly useful if your current mortgage deal is ending soon, or if you want to understand how recent market movements may affect your borrowing options.
